
Homeowners Can Access Home Equity Without Monthly Payments and Keep their First Mortgage
Coke Vs Pepsi
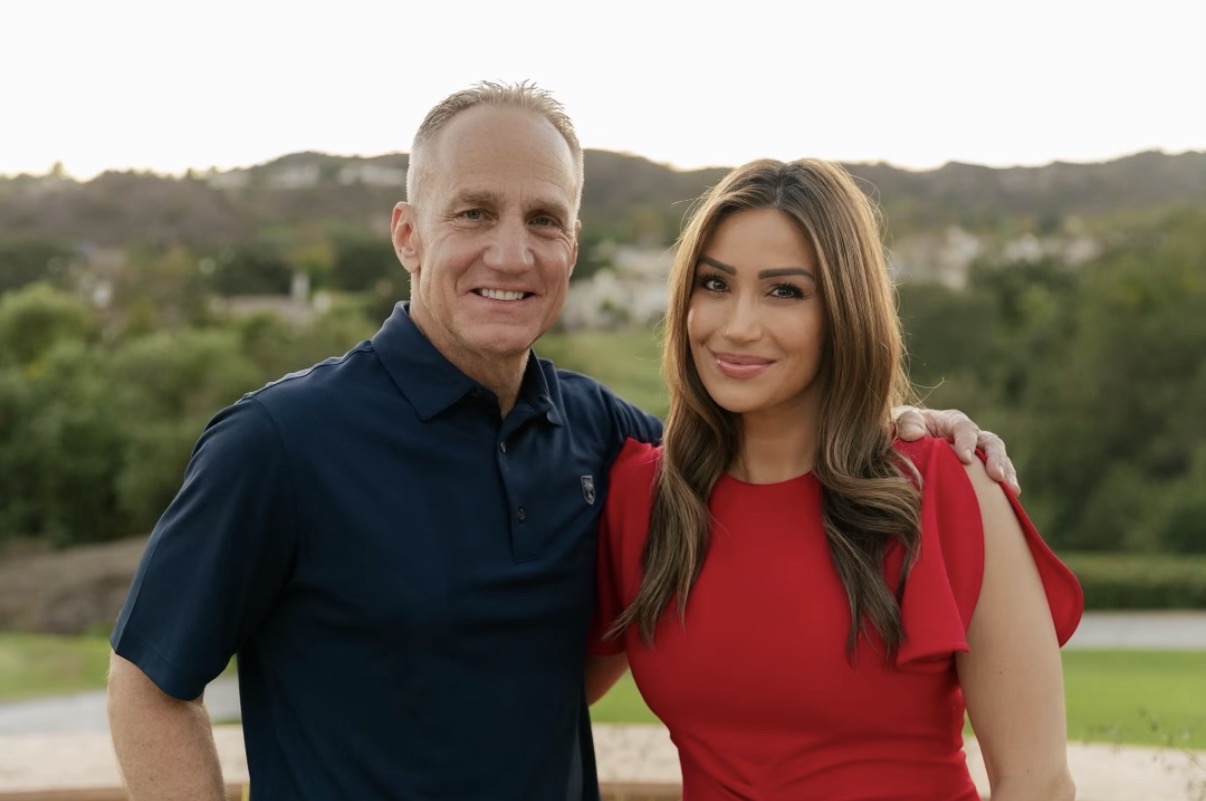
Paul and Sarah Scheper, Father Daughter Dream Team
BBB Accredited
Make the math decide
Homeowners with Below-Market Mortgages Should Keep Those No Matter What
ORANGE COUNTY, CA, UNITED STATES, October 19, 2026 /EINPresswire.com/ -- Millions of American homeowners have accumulated substantial home equity while enjoying first-mortgage interest rates that may be foolish to replace in today's lending environment. For homeowners with mortgages at 5% or lower, refinancing a below-market rate mortgage simply to access additional cash may be a costly financial decision.
According to Paul E. Scheper, CRMP, CSA, SRES, President of Loangevity Mortgage, the first rule of accessing home equity is simple: Don't unnecessarily sacrifice a great first mortgage.
"If a homeowner has a first mortgage at 5% or lower, it's a must to protect that mortgage whenever possible," says Scheper. "If a homewowner needs to access their home equity, don't pay off a great loan. Find a company that can help compare a traditional Home Equity Line of Credit (HELOC) or Home Equity Loan (HELOAN). If one of these plans work, then these are often the most economical and straightforward ways to access your equity without disturbing your existing first mortgage."
However, Scheper points out that not every homeowner can qualify for a conventional HELOC OR HELOAN. Some have insufficient qualifying income, credit challenges, or financial circumstances that make traditional underwriting difficult. Others simply want to avoid adding another required monthly payment to their household budget.
Fortunately, if a homeowner needs to tap equity without disturbing their below-market first mortgage, two solid alternatives deserve serious consideration if a HELOC or HELoan are not possible. Scheper suggests that consumers reach out to a reputable mortgage company that can offer both of these options below:
HEI — Home Equity Investment: A shared-equity arrangement that provides cash today in exchange for an agreed-upon financial interest tied to the home's future value or appreciation.
HEDIL — Home Equity Deferred Interest Loan: This is also called a reverse second mortgage that allows eligible homeowners to borrow against their equity while deferring principal and interest payments until a future repayment event. It's simply a 2nd loan with deferred interest.
Both approaches can preserve an attractive existing first mortgage, provide cash without additional required monthly payments on the new arrangement, and offer alternatives to homeowners who may not qualify for traditional financing. But how each program works — and what homeowners ultimately owe — can be different, so it it prudent to compare each plan.
The HEI: Sharing Future Home Equity With an Investor
A Home Equity Investment is not a traditional mortgage loan. Instead, an investment company provides funds to a homeowner in exchange for a contractual share of the home's future value or appreciation. There are no required monthly payments to the HEI provider. The homeowner generally continues making payments on any existing first mortgage and remains responsible for property taxes, insurance, and maintenance.
The HEI is settled at a future date, typically when the homeowner sells the property, refinances, buys out the investment, or reaches the agreement's contractual maturity. The term is usually the greater of your remaining term, or 10 years.
One important distinction is that the amount ultimately owed is tied to the contractual equity-sharing formula rather than a traditional mortgage interest rate. If the home's value increases substantially, the investor's return may increase substantially as well. Look for a safety cap, which can protect homeowners. Depending on the agreement, the investor may also participate in a decline in property value, although contractual adjustments, minimum returns, caps, and other provisions vary. HEI programs may be attractive to homeowners who have difficulty qualifying for traditional loans because of income documentation or credit limitations. Sometimes, sharing equity with an investor might be cheaper than paying deferred interest to a bank.
The HEDIL: A Loan with Deferred Interest Paid to Bank Later
A Home Equity Deferred Interest Loan, or HEDIL, is a different approach. It is a reverse second mortgage from a bank (not an investor) that allows eligible homeowners to borrow against their property while preserving an existing first mortgage. Unlike an HEI, the homeowner does not contractually share future appreciation with an investor. Instead, the homeowner borrows a defined amount, and interest accumulates on the outstanding loan balance over time. These are loans, with a fixed rate, and not a line of credit. There are no required monthly principal and interest payments on the reverse second mortgage while the borrower continues meeting the loan's occupancy and other obligations. The loan is generally repaid when the homeowner sells, permanently leaves the property, passes away, or another contractual repayment event occurs.
"The important distinction is ownership of future appreciation," Scheper explains. "With a deferred-interest reverse second mortgage (HEDIL), a homeowner can retain 100% of their home's future appreciation. With an HEI, consumers access equity from an investor, in exchange for agreeing to share a percentage of their home's future value." continues Scheper. With both programs, eligible borrowers must continue paying their existing first mortgage, property taxes, homeowners insurance, and applicable HOA assessments, and must keep the property in good working order.
Scheper believes homeowners should compare both programs before making a decision. "It's like the Coke versus Pepsi Challenge," says Scheper. "Both can be good choices for the right homeowner, but it's always smart to taste-test (get the numbers) from a mortgage company that can offer both programs.
The distinction can become especially meaningful for homeowners who expect to remain in their homes for many years or believe their properties will appreciate significantly. An HEI may become more expensive if property values rise substantially. Conversely, a deferred-interest mortgage balance continues growing through accumulated interest, even if the home's value remains flat. The homeowner's expected holding period, anticipated appreciation, qualification requirements, repayment terms, and estate-planning objectives all deserve careful consideration.
HEI vs. HEDIL: Let the Numbers and Math Decide
Unlike companies that offer only one home equity solution, Loangevity Mortgage, and other mortgage companies, offer both programs. This allows homeowners to access to all four alternatives, usually in this order: HELOCs, HeLOANs, Home Equity Investments (HEIs), and Home Equity Deferred Interest Loans (HEDILs). Loangevity's approach is program-agnostic. The company compares available alternatives to help homeowners identify the most appropriate, suitable, and financially sustainable solution.
"We don't care which program wins the comparison," says Scheper. "We offer both HEI and HEDIL programs, so we simply run the numbers both ways, year by year, and let homeowners see the projected outcomes for themselves." Scheper recommends comparing the projected financial obligations of an HEI and a HEDIL every single year for 10, or 15, or 20 years, using comparable net cash proceeds and consistent assumptions about future home appreciation.
The free analysis illustrates the projected payoff obligations, future home values, and, most importantly, projected remaining home equity under each arrangement.
"The program that looks better in year five might not be the better choice in year fifteen," Scheper explains. "That's why homeowners need to see the numbers for the first 20 years. Mortgage companies need to show customers how much equity they may retain under either program." Homeowners need to ask their mortgage loan officer what do the numbers look like year by year. Homeowners need to make make sure they get an illustration of what happens under both programs over time, so they can make an informed decision based on projections rather than today's guesses.
"If you can qualify for an affordable HELOC or HELOAN, it's prudent to consider those options first," says Scheper. "But if a homeowner cannot qualify, or they simply don't want another required monthly payment, then it's smart to compare an HEI against a HEDIL. Homeowners should compare things apples to apples, preserve their low-rate first mortgage, access the equity they've worked hard to build, and select the most appropriate, suitable, and sustainable financial solution. I suggest that consumers find a company who can offer both programs and compare things to help the homeowner decide what is best. Eligibility for individual programs varies based on age, credit, property characteristics, and other underwriting requirements.
Free HEI vs. HEDIL Home Equity Comparison
Loangevity Mortgage and almost all companies offer homeowners a 20-year, side-by-side home equity comparison. Homeowners can see projected future obligations and remaining home equity under both arrangements, year by year, using consistent assumptions about property appreciation. "Your home may be your single largest financial asset, and before agreeing to share future equity or accumulate deferred interest, take the time to compare both. Find a company to run the numbers for both programs. It's prudent to compare before you commit.
About Loangevity Mortgage
Loangevity Mortgage is an Orange County, California-based mortgage company helping homeowners and homebuyers explore residential mortgage financing, reverse mortgages, second mortgages, home equity solutions, and alternative lending programs. Led by Paul and Sarah Scheper, the company emphasizes consumer education, personalized free comparisons, and helping clients understand their financing options.
Holly Hackett, Press and Media Director
Loangevity Mortgage
+1 800-662-6784
www.BetterCallPaul.Mortgage
Visit us on social media:
LinkedIn
Instagram
Facebook
YouTube
X
Other
Legal Disclaimer:
EIN Presswire provides this news content "as is" without warranty of any kind. We do not accept any responsibility or liability for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this article. If you have any complaints or copyright issues related to this article, kindly contact the author above.
